Merchant Cash Advance vs Term Loan: What Each Actually Costs
19 November 2026
By Rupert Hogan, Founder & CEO of BusinessLoans.ie
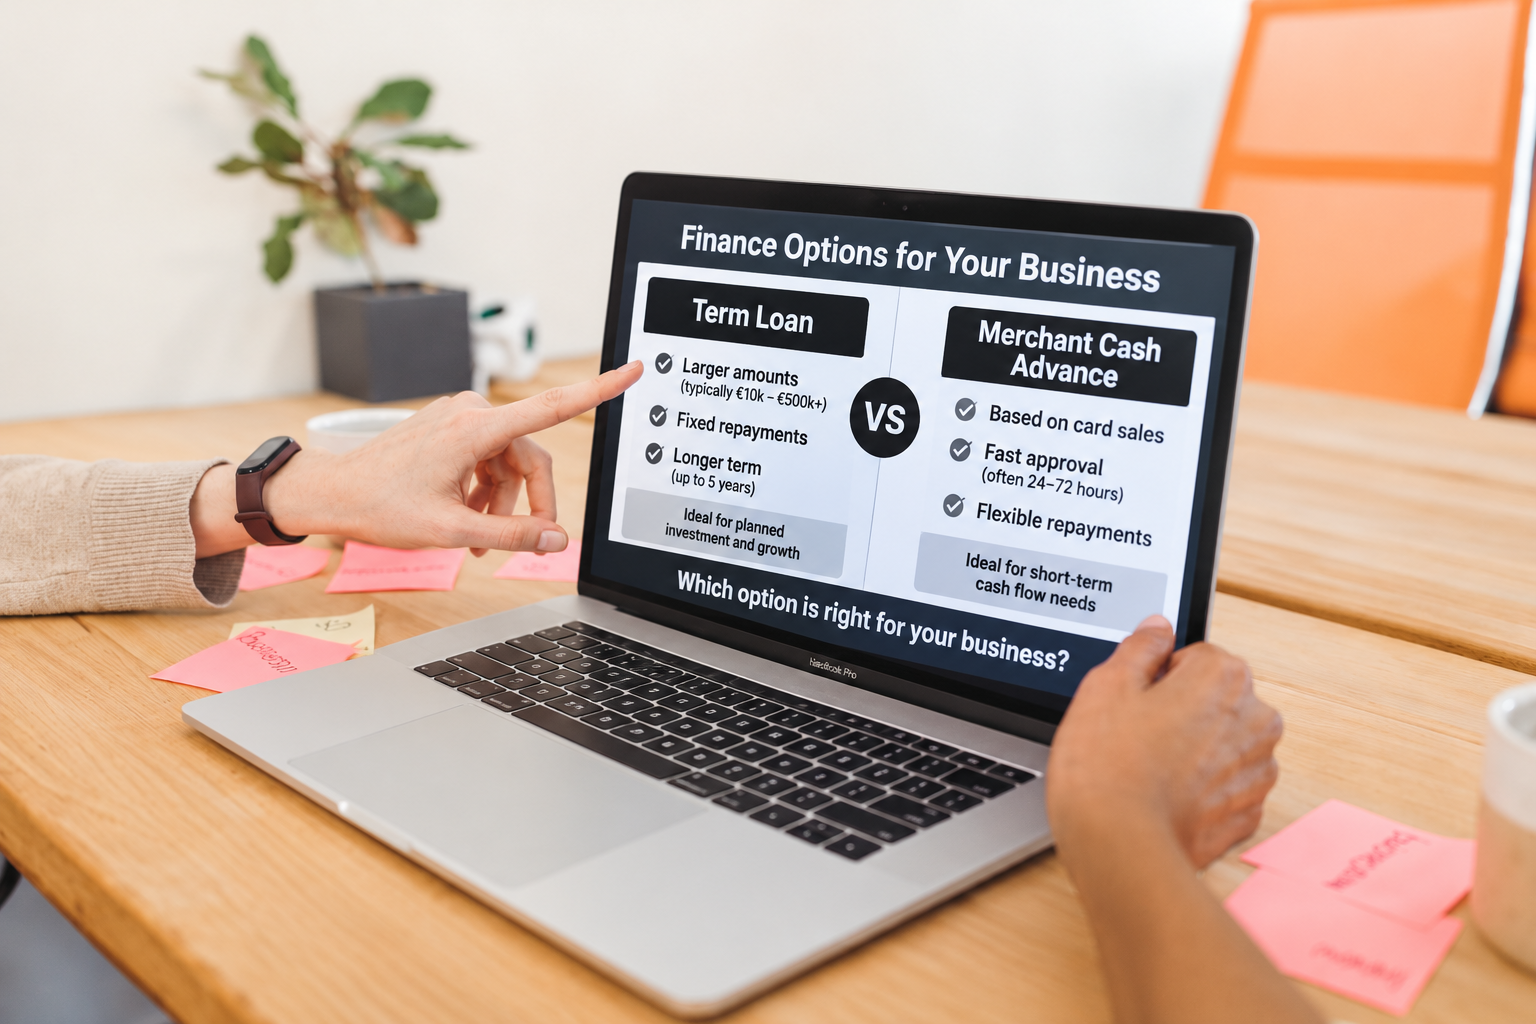
Quick Summary
- A term loan normally charges interest on the outstanding balance. An MCA often uses a factor rate to set the total amount payable upfront.
- In a recent gym offer, a €60,000 advance at factor 1.21 meant €72,600 payable: a €12,600 funding cost before any extra charges. At close to €70,000 a month in card takings, that is roughly 10.4 months of collections.
- The offer's 10% of daily card income was the collection share, not a 10% interest rate. Factor 1.21 is not 21% APR either.
- Most merchant cash advances are repaid within a maximum of 12 months, while a term loan can run for years. The repayment period is part of the cost comparison.
- Banks are often the lowest-cost starting point. Non-bank options can offer quicker, clearer decisions and funding for different trading profiles, but fees matter.
- Compare cash actually received, total euro cost, repayment pressure in a quiet month and early-settlement terms — not just a headline rate.
Table of Contents
- How the two costs work
- Published bank business loan rates
- Non-bank interest rates and fees
- The €60,000 gym MCA offer
- A €60,000 term-loan illustration
- Compare the full cost and cash flow
- Why businesses choose a higher-cost option
- Trading history and lower-cost stepping stones
- Renewals: the facility can grow with the business
- Can business borrowing costs reduce taxable profits?
- Documents and questions to have ready
- Frequently Asked Questions
Merchant cash advance vs term loan: how the costs work
Two offers can put the same amount into your business account and still behave very differently. One asks for scheduled loan repayments. The other takes a slice of card income as it comes in. The useful question is not simply “Which rate looks lower?” It is “What will this cost, and will the business still have enough cash after repayments?”
A business term loan usually charges interest on the balance still owed. Each scheduled repayment pays interest and reduces capital. With a variable rate, repayments or the cost can change; a fixed rate gives more certainty within its terms. An establishment or facility fee may sit on top.
A merchant cash advance often sets a total repayment using a factor rate: advance multiplied by factor. Collections may then be an agreed percentage of eligible card receipts until that balance is cleared. The factor sets the euro cost; the collection percentage determines how cash leaves the business.
Neither a nominal loan interest rate nor an MCA factor is automatically an all-in APR. For the wider mechanics, read our merchant cash advance guide.
Published bank business loan rates in Ireland
If you qualify and the timing works, a main bank is often a sensible first stop for a lower-cost business loan. That is not a claim that a bank is always cheapest: your actual offer, fees, security and any eligible support scheme determine the result.
| Lender | Published annual rate | Scope and fees to check |
|---|---|---|
| Bank of Ireland | 7.02% variable | Standard business loans from €1,000 to €120,000, unsecured terms up to 7 years and no arrangement fee. Personal guarantees may apply. |
| PTSB | 7.50% variable | Business term/cash-flow lending from €5,000. A facility fee of up to 1% may be charged at the bank's discretion. |
Sources checked on 19 November 2026: Bank of Ireland business loans, PTSB's October 2026 business lending rate sheet and PTSB term-loan fees and conditions. Rates can change and lending assessment applies.
Bank of Ireland discusses larger facilities separately, with different pricing and security requirements. Do not assume its 7.02% standard small-business rate applies to a €500,000 request. Likewise, the bank's advertised seven-year term is not the term available from every lender: sole-trader unsecured term loans arranged through us have a maximum of three years.
Ask about early settlement too. Variable and fixed-rate terms can differ; where a fixed-rate offer applies, check whether breakage costs arise. Do not assume a penalty applies to every PTSB business loan, or that every loan can be cleared free of charge.
Non-bank term loans: the rate is only part of the price
Linked Finance publishes term-loan interest rates from 7.95%, depending on credit grade. Flurish's FAQs publish rates from 8.45%, depending on loan type, amount and financial profile. These are starting rates, not a promise of your offer or a like-for-like all-in cost comparison.
In offers we see, a lender's establishment fee can be a little over 5%, but the exact percentage and treatment must come from the offer. Do not assume one standard fee applies to all Linked Finance or Flurish loans. “Free to apply” also does not mean the funding has no lender fees.
There are two important fee methods:
- Fee added to the borrowing: you receive the requested cash, but start with a larger debt. If interest applies to that financed fee, it increases interest as well as capital repayments.
- Fee deducted from the gross loan: the amount arriving in your account is smaller than the headline loan amount. Flurish's published FAQs describe this method, along with possible monthly servicing and late-payment fees. Check the exact deductions before accepting.
Pro Tip: Ask “How much actually lands in my account, and what is the total I pay back?” Those two figures cut through a lot of confusing rate language.
A recent gym offer: €60,000 at factor 1.21
A gym client recently received an MCA offer with a €60,000 advance, factor 1.21 and collection of 10% of daily card income. This is an anonymised offer example, not a confirmed completed loan or a standard rate available to every gym.
| Item | Figure |
|---|---|
| Advance | €60,000 |
| Factor | 1.21 |
| Total payable: €60,000 × 1.21 | €72,600.00 |
| Funding cost before any additional charges | €12,600.00 |
| Collection share | 10% of daily eligible card income |
So €100 of eligible card income produces a €10 collection; €1,000 produces €100. That is not interest charged that day. It is money going towards the agreed €72,600 total. It is also a share of sales, not of profit: rent, wages, tax and other costs still need to come out of the remaining cash.
How long might the collections take?
The actual offer's repayment duration was not supplied. The middle line below uses close to €70,000 a month in card takings — the card volume used for this example, not a figure lifted from the client's statements. The other lines are hypothetical constant-sales scenarios, and none of them is a contractual repayment schedule. They assume the full €72,600 is collected solely through the 10% share, with no extra charges, minimum collections, refunds or changes in sales. Most merchant cash advances are structured to be repaid within a maximum of 12 months, so read these lines as the arithmetic behind a collection share rather than a schedule a lender would necessarily write.
| Monthly eligible card income | Monthly collection at 10% | Approximate time to collect €72,600 |
|---|---|---|
| €40,000.00 | €4,000.00 | 18.1 months |
| €70,000.00 | €7,000.00 | 10.4 months |
| €120,000.00 | €12,000.00 | 6.0 months |
At close to €70,000 a month in card takings, the illustration takes about 10.4 months — inside the 12-month window most merchant cash advances are designed to clear within. Stronger sales clear it sooner. A business taking close to €40,000 a month would need about 18 months at the same 10% share, and a lender sizing a facility against takings that low would usually ask for a higher collection share, set minimum collections or offer a smaller advance rather than let collections run for a year and a half. If the agreed fee stays the same, quicker repayment does not automatically save €12,600: it shortens the period over which that cost is paid, increasing the annualised cost. Factor 1.21 must not be labelled 21% APR.
Watch Out: A product called an MCA may still have minimum collections, fixed payments, processor conditions or guarantees. Check the agreement, including what happens if sales fall sharply and whether early settlement earns a rebate.
A €60,000 term loan: an illustration with a financed fee
To show how fees change a term loan, assume €60,000 cash received, a 10% nominal annual interest rate, 36 monthly repayments and a hypothetical 5.25% fee added to the debt. Interest applies to the whole opening balance. This is not a quote from Linked Finance, Flurish or any other lender, and 10% is not an all-in APR.
- Establishment fee: €3,150.00.
- Opening loan balance: €63,150.00.
- Monthly capital-and-interest repayment: approximately €2,037.67.
- Total repayments over 36 months: approximately €73,356.22.
- Interest within those repayments: approximately €10,206.22.
- Full funding cost relative to €60,000 received: approximately €13,356.22, comprising fee plus interest.
We assume a constant rate, monthly interest at the annual rate divided by 12, no other charges and no early settlement. Totals use unrounded instalments; a real schedule may have rounding adjustments. If the fee were deducted instead, the cash received and comparison would change.
Compare the euro cost and the cash-flow squeeze
| Point | Gym MCA offer example | Hypothetical term loan |
|---|---|---|
| Cash received, assuming no deductions | €60,000 | €60,000 |
| Total payable | €72,600.00 before extra charges | About €73,356.22 |
| Funding cost | €12,600.00 before extra charges | About €13,356.22 |
| Cash leaving the business | 10% of eligible daily card income | About €2,037.67 monthly |
| Duration | Sales-dependent; most MCAs are repaid within a maximum of 12 months. About 10.4 months at close to €70,000 monthly card income | 36 months in the illustration |
This is not a like-for-like annualised price comparison: the MCA is a supplied offer; the loan is hypothetical and runs over a different period. Similar total euro costs do not mean similar annual costs or repayment pressure. At close to €70,000 monthly card income, MCA collections are about €7,000 a month — roughly three and a half times the illustrated loan instalment, even though the advance clears sooner.
Compare offers for the same net cash requirement and purpose. Include every fee, the expected duration and early-settlement rules. Then test the weakest recent month. A 10% sales deduction can be uncomfortable in a low-margin business; a fixed loan instalment can be uncomfortable in a seasonal one.
Why take a higher-cost option when a bank rate is lower?
Many business owners who contact us have already tried their bank. Some find the information requests too much hassle; others have waited weeks or months and feel they are getting the “slow no”. That is their experience, not a claim that every bank application takes that long. A clear bank offer that arrives in time can be a good outcome.
The specialist and non-bank options we help with focus on quick decisions — whether that decision is yes or no — and usually a few easy-to-get documents. Timing still depends on the lender and a complete application. Approval is not the same as funds arriving.
Banks can fund lending partly from customer deposits. Non-bank lenders generally do not have that same deposit funding base: they source money through investors, institutions or other market funding. Their own funding costs and the business risks they accept help explain why prices can be higher.
The commercial test is whether acting now creates enough value to justify the extra cost. Funding a proven profitable opportunity or repairing essential equipment is different from repeatedly borrowing to cover losses. Speed is useful; it does not make expensive borrowing affordable.
Trading history can open up cheaper options
MCA options through BusinessLoans.ie can be considered from 90 days trading, with typically at least €5,000 monthly card takings, supported processing and provider assessment. Those minimums do not imply that a €60,000 advance is available at that level of sales.
For unsecured term loans through us, the starting profile is at least one full year's completed accounts, €100,000 annual turnover, a net profit and no recent missed bank-statement payments. Lenders can ask for a longer history. The loan is not registered against property or assets; some lenders ask directors for a personal guarantee.
Sole traders and companies do not necessarily have the same options. Our sole-trader unsecured term loans run for a maximum of three years, and the latest accounts need positive business net worth as well as turnover and profit. Some named providers only lend to limited companies. Read our sole-trader term-loan guide.
Shorter-term funding can be a stepping stone as completed accounts and repayment history build. Lower-cost finance may then become available, but future approval or refinancing is not guaranteed. Make sure the first facility works on its own rather than relying on a cheaper replacement later.
If most customers pay by bank transfer, consider flexible repayment funding or eligible invoice finance instead of forcing an MCA to fit. For equipment, compare asset finance. Our business finance overview explains the wider choice.
Renewals: the facility can grow with the business
Many of the businesses we help do not use an advance once and disappear — they renew. A first facility that carried a quiet quarter becomes the reference point for the next one, and a lender that has watched a year of your card takings knows the business far better than it did on day one.
Renewal offers are based on the volume of card sales at that time. If the business has grown, the offer can get bigger: more card takings usually support a larger advance. If trading has dipped, the renewal will normally be smaller. The same assessment applies each time, so a renewal is not an automatic top-up or a guarantee of approval.
Renewing is also where the stepping-stone point earns its keep. Steady card takings and a clean repayment record are what make the lower-cost options above reachable as completed accounts build up.
Can business borrowing costs reduce taxable profits?
Revenue's business-expenses guidance includes interest on money borrowed to finance your business as an expense that may be deducted in calculating profits. Sole traders normally claim business expenses through Form 11; companies through Form CT1. Only the business-use portion qualifies where borrowing has mixed business and private use.
A deduction reduces taxable profit; it is not a refund of the whole borrowing cost. Repaying the loan capital itself is not an interest expense. The tax treatment of an MCA's fixed charge and lender fees depends on the agreement and accounting treatment: do not automatically treat the whole MCA collection, or even every funding charge, as deductible interest.
Ask your accountant to separate capital, interest and fees and confirm the treatment for your trade and business structure. Keep the cash-flow comparison based on gross payments too: potential tax relief does not put money back into your account on each collection day.
A few documents — and the right questions
For an MCA, have recent card-processing statements, business bank statements, identification and existing finance details ready. For a term loan, add completed accounts and tax clearance where requested. Sole traders need properly prepared accounts with a profit and loss and a reasonably detailed balance sheet; Form 11 alone is not enough for the term lenders we work with.
- How much cash arrives after deductions?
- What is the total euro amount payable, including every fee?
- Is the rate annual interest, an all-in APR or a factor?
- Is the lender fee financed or deducted, and does it attract interest?
- What leaves the account in a quiet week or month?
- What happens if sales drop, and what guarantees or minimum payments apply?
- What would it cost to settle early?
At BusinessLoans.ie, one application goes to several suitable lenders and returns the offers that fit. We help you look beyond the rate to the money received and the repayment commitment. Free to you. Lenders pay us a commission when your loan completes. Lender interest, fees and MCA charges still apply; see how we get paid.
Frequently Asked Questions
Is a merchant cash advance more expensive than a term loan?
Often it is, particularly compared with a lower-rate bank loan, but compare actual offers. A factor rate, annual interest rate and lender fee percentage measure different things. Net cash received, total charges and repayment timing all matter.
Does factor 1.21 mean 21% APR?
No. It means the agreed total is 1.21 times the advance before any additional charges: €72,600 on €60,000. An annualised comparison also needs the timing and amounts of repayments and all fees.
Is the 10% card deduction the interest rate?
No. It is the collection share. In the gym offer, 10% of eligible daily card income goes towards the total balance. The factor 1.21 sets the total payable; the card percentage affects collection speed and cash flow.
Will clearing an MCA early reduce the cost?
Only if the agreement provides a rebate or other reduction. A fixed total can stay the same even when strong sales clear it quickly. Ask for the early-settlement calculation in writing.
Can a sole trader get these options?
Suitable MCA and term-loan options can be considered for sole traders, but provider criteria differ and some lenders only fund companies. Sole-trader unsecured term loans arranged through us have a maximum three-year term and need detailed accounts, profit, positive business net worth and affordability.
Can interest and MCA charges be claimed against tax?
Interest on borrowing used for the business trade may be deductible under Revenue's rules. Capital repayments are not interest expenses. Ask your accountant about MCA charges and lender fees rather than assuming they receive identical treatment.
How long does a merchant cash advance take to repay?
Most merchant cash advances are repaid within a maximum of 12 months, because collections come out of ongoing card income rather than a long scheduled loan term. The exact period still depends on your card volumes and the agreed collection share, so ask for the expected repayment timeline at your current takings before accepting.
Do offers get bigger if I renew?
Renewal offers are based on the volume of card sales at the time of the renewal, so a business taking more by card than when it first applied can usually be offered a larger advance. Weaker card takings would normally mean a smaller one. Every renewal still goes through assessment; it is not an automatic top-up.
Can I apply after 90 days trading?
An MCA may be considered from 90 days with typically €5,000 or more in monthly card takings and provider assessment. Established-business term loans need at least a full year's completed accounts and other criteria. Neither starting point guarantees approval or a particular amount.
General business-finance information, not personal lending or tax advice. Published rates checked on 19 November 2026; offers and terms can change. The gym example is a recent offer, the sales scenarios and term loan are illustrations, and finance is subject to lender assessment.
Ready to get funded?