Menu
Bakeries & bakery businesses · Ireland
Bakery
business loans.
Replace an oven, add a mixer or pay for ingredients and packaging before the next busy period. We help Irish bakeries compare equipment finance and business loans through specialist and non-bank lenders, with different options for shop-counter card sales and wholesale customers who pay on account.
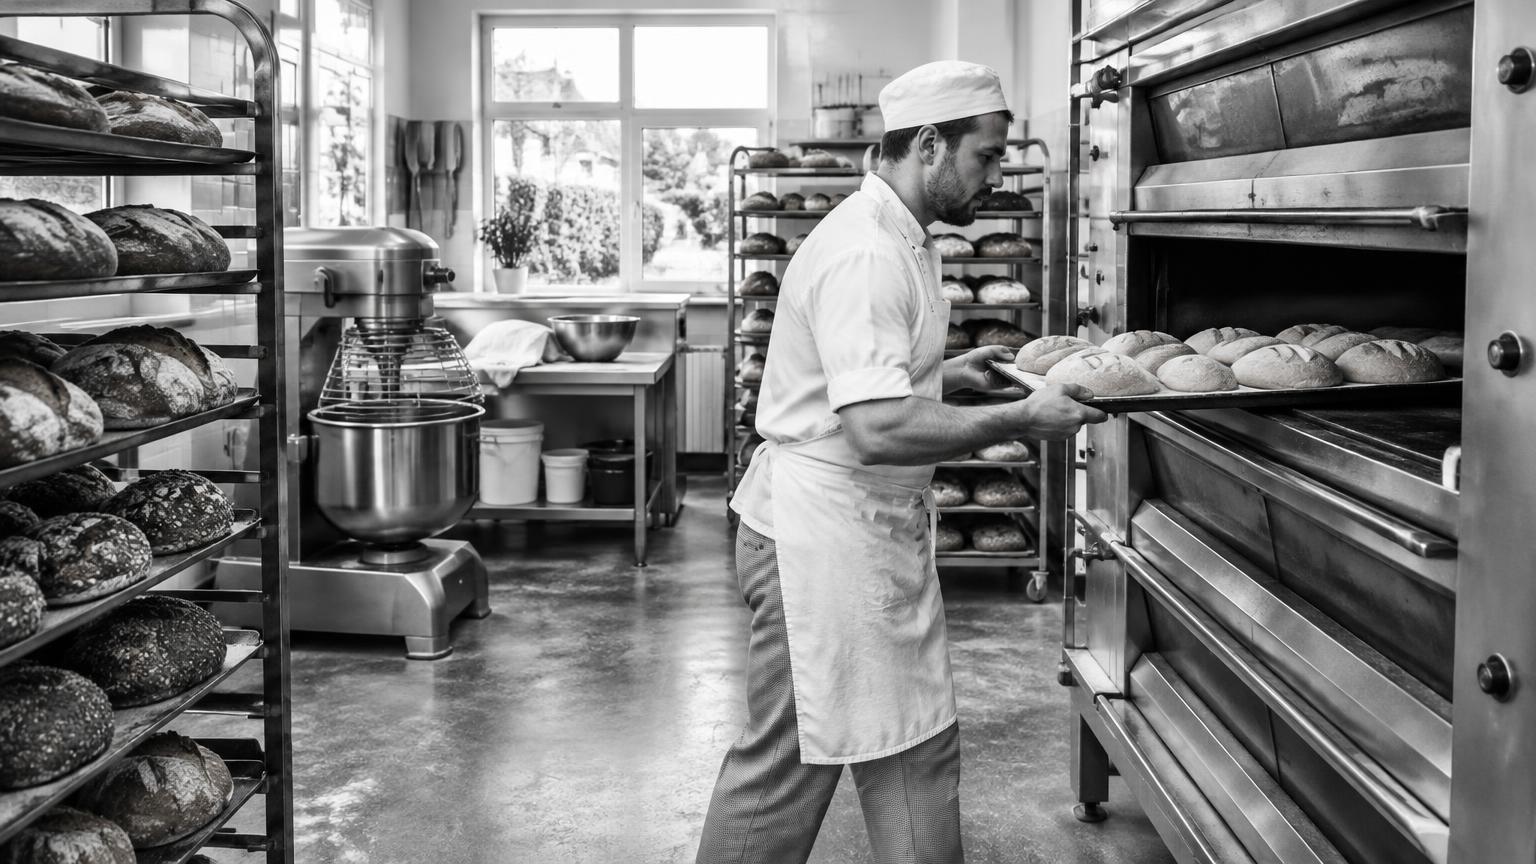
Ovens & bakery equipment
For suitable machinery used to bake, prepare and store your products.
- Eligible commercial ovens, mixers, dough dividers and proofing equipment
- Suitable refrigeration, packaging machinery and display equipment
- Leasing or hire purchase on suitable new or used equipment
- Equipment-finance deals from €10,000, typically with a 10% dealer deposit
- Smaller equipment packages depend on the items and lender
- Include installation costs in the supplier quote for review
Card-sales working capital
For bakeries with regular card takings from retail customers.
- Merchant cash advance can be quoted from 90 days trading
- At least €5,000 monthly card takings
- May help with ingredients, packaging, wages and other business costs
- Collections are linked to an agreed percentage of card sales
- The collection percentage is not the interest rate or total borrowing cost
- Check the total amount repayable and effect on daily cash flow
Term loans for costs & growth
For established bakeries funding production, premises and a growing workload.
- Flour, butter, ingredients, packaging, wages and energy costs
- Recruitment, shop improvements, marketing and expansion
- At least 12 months trading and one full year's completed accounts
- Latest accounts showing €100,000 or more turnover and a net profit
- No recent missed payments on business bank statements
- The lender assesses affordability and existing commitments
Wholesale invoices & payment gaps
For supplying shops, cafés, hotels and other business customers on credit terms.
- Invoice finance may suit qualifying unpaid business-to-business invoices
- A wider ledger facility may suit recurring wholesale deliveries
- One-off or ad hoc invoices from €100,000
- Customer quality, returns, credits and payment terms affect eligibility
- Retail card sales and future orders are not the same as eligible invoices
- Flexible repayment loans may suit businesses from 9 months trading with steady cash flow and around eight or more deposits a month
Business finance only, not personal loans. Unsecured term loans are not registered against property or business assets, but some lenders ask for a personal guarantee. All options depend on lender assessment, purchase suitability and affordability.
Match the funding to how you sell
A shop selling bread and cakes by card has a different cash cycle from a wholesale bakery waiting for customers to settle invoices. Compare merchant cash advance for eligible card-sales businesses with invoice finance for qualifying wholesale invoices. For production equipment, explore asset finance, or term and flexible repayment loans for wider costs.
Our food and drink producer finance, retail finance and restaurant finance pages cover related businesses. If you are opening your first bakery, see new-business finance.
Taking card payments? Compare eligibility, repayments and costs on our merchant cash advance page.
Guides for your industry
16 October 2026
How to Secure Equipment Finance in Ireland: A Guide
Table of Contents How to Secure Equipment Finance in Ireland: Step-by-Step What You'll Need Before You Apply Types of Equipment Finance Available Equipment Finance Application Requirements Documents Lenders Typically Ask
Read guide →
3 November 2026
Is a Merchant Cash Advance Right for Your Irish Business?
How merchant cash advances work in Ireland: card-sales repayments, costs, eligibility from 90 days trading and the alternatives to compare before applying.
Read guide →
20 October 2026
Business Loan With Seasonal Cash Flow: A Practical Guide
How seasonal Irish businesses can borrow well: loan types that suit uneven income, building a cash flow forecast lenders trust, and repayments that match your trading year.
Read guide →
2 November 2026
Invoice Finance Ireland for Growing SMEs
Release cash tied up in unpaid B2B invoices. Understand factoring, invoice discounting, lender fees and the documents Irish SMEs need.
Read guide →
Common questions
Can I finance a commercial oven or mixer?
Suitable new or used bakery equipment may qualify for leasing or hire purchase. Send a supplier quote showing the machinery, age and value, with installation costs included for review. The lender checks equipment suitability and affordability; not every small item or installation cost qualifies.
Can card sales help my bakery qualify for funding?
Merchant cash advance can be quoted from 90 days trading with at least €5,000 monthly card takings. Approval depends on the lender's assessment and existing commitments. Collections use an agreed percentage of card sales, but that percentage is not the borrowing cost. Compare the total repayment amount before accepting.
Can a business loan cover ingredients and energy bills?
A term loan may cover ingredients, packaging and wider business costs for an established bakery. You need at least 12 months trading and one full year's completed accounts, turnover of €100,000 or more, a net profit and no recent missed payments. Affordability and existing commitments also matter.
Can I fund invoices from cafés or retailers?
Invoice finance may suit qualifying business-to-business invoices for products already supplied. One-off or ad hoc invoices start at €100,000; a wider ledger facility is another option. The lender reviews customers, terms, returns and credits. Do not assume disputed invoices or future orders qualify.
What if I need to bake ahead of Christmas or another busy period?
Plan when ingredients and packaging must be paid for, staffing needs and when sales receipts will arrive. Allow for shelf life, wastage and quieter weeks after the busy period. Compare repayments with realistic cash flow rather than assuming every batch sells immediately.
Can you help with a bakery delivery van?
We can look at asset finance for an eligible business van. Include any specialist conversion in the dealer quote for lender review. Vehicle age, value, supplier and affordability determine the options.
Can a new bakery apply?
A bakery with sufficient card takings may be considered for merchant cash advance from 90 days trading. Equipment criteria vary, while term loans need one full year's completed accounts and the turnover and profit criteria. For a pre-trading bakery, our new-business page points to banks, Microfinance Ireland and the National Enterprise Hub.
What should I send to get started?
Send recent business bank statements, the amount needed and its purpose. Include card-processing statements for merchant cash advance, equipment quotes for machinery and latest completed accounts for a term loan. For wholesale invoice finance, include an aged debtor ledger and sample customer invoices and terms.
Do you charge a broker fee?
No. We do not charge clients a fee; lenders pay us a commission when funding completes. Lender interest and charges are separate and should be checked before accepting an offer.
Free to you. Lenders pay us a commission when your loan completes. How we get paid