Menu
Builders’ merchants & building suppliers · Ireland
Builders’ merchant
& supplier finance.
Stock needs paying for before it is sold, and trade-account customers may pay after the goods leave your yard. We help Irish builders’ merchants and building-material suppliers compare stock funding, invoice finance and business loans through specialist and non-bank lenders, so supplier payments and customer credit terms do not squeeze everyday cash flow.
Stock & supplier payments
For buying and reselling physical building materials.
- Eligible supplier invoices for timber, insulation, roofing, plumbing and other resale stock
- The trade finance lender pays the supplier; BusinessLoans.ie arranges the facility
- Repayment terms up to 180 days, subject to approval and agreed terms
- Target profile: at least 12 months trading and around €500,000 annual sales
- Ideally profitable, with supplier and transaction checks still required
- Match the repayment date to stock turnover and expected customer receipts
Customer trade-credit gaps
For eligible sales already invoiced to business customers on account.
- Invoice finance may release cash from qualifying unpaid business-to-business invoices
- A wider ledger facility may suit recurring trade-account sales
- One-off or ad hoc invoices from €100,000
- Customer quality, debtor concentration and credit terms affect eligibility
- Explain overdue balances, disputes and credit notes before applying
- This funds eligible receivables; it does not insure you against customers failing to pay
Term loans & working capital
For established merchants funding stock, expansion and wider business costs.
- Stock purchases, staffing, branch improvements and growth costs
- At least 12 months trading and one full year's completed accounts for term loans
- Latest accounts showing €100,000 or more turnover and a net profit
- No recent missed payments on business bank statements
- Flexible repayment options from 9 months trading with steady cash flow and around eight or more deposits a month
- The lender assesses affordability, existing facilities and commitments
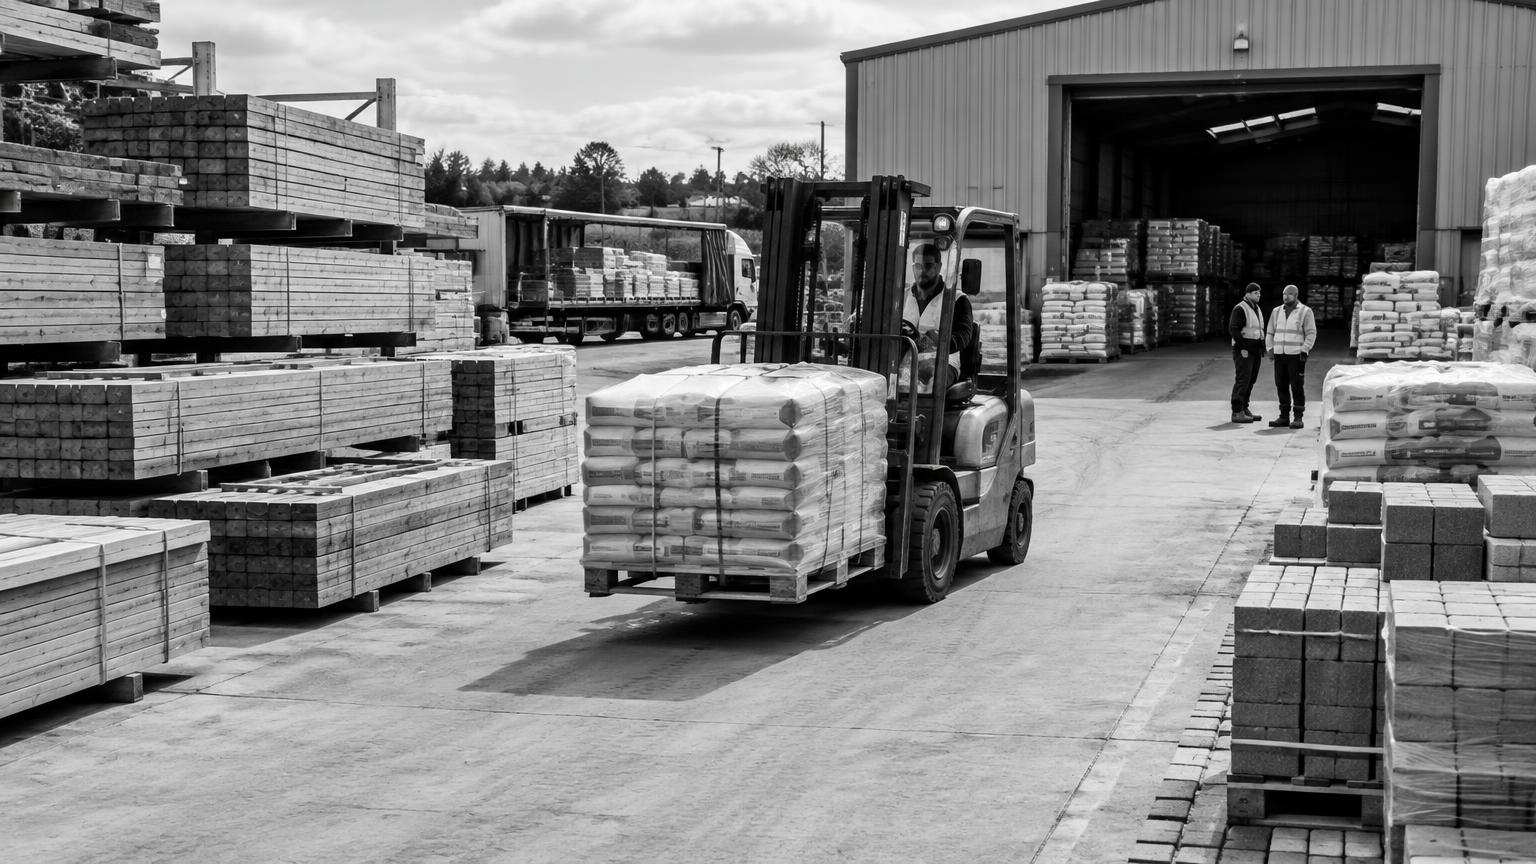
Yard equipment & vehicles
For suitable equipment that keeps deliveries and stock handling moving.
- Eligible forklifts, handling machinery and business vehicles
- Leasing or hire purchase for suitable new or used equipment
- Some smaller eligible equipment has no-deposit leasing options, subject to lender criteria
- Other equipment-finance deals from €10,000, typically with a 10% dealer deposit
- Equipment age, value, supplier and affordability determine the options
- Send a supplier quote and compare deposits, VAT timing and total repayments
Business finance only, not personal loans. Supplier trade credit, trade finance and invoice finance are different arrangements; funding does not remove customer credit risk. Unsecured term loans are not registered against property or business assets, but some lenders ask for a personal guarantee. All options depend on lender assessment and affordability.
Fund the gap between buying and getting paid
Start with when the supplier must be paid, how long the stock is likely to sit in the yard and when trade-account customers will settle. Trade finance can address eligible stock purchases, while invoice finance relates to qualifying sales already invoiced. Compare the funding cost with the margin on the materials, not just the size of the facility.
For wider business costs, explore term and flexible repayment loans, or asset finance for suitable machinery and vehicles. See our importer and wholesaler finance and construction finance pages for related funding needs.
Guides for your industry
4 November 2026
Trade Finance in Ireland: Get Your Stock Funded and Take Up to 180 Days to Pay
Buying stock before customers pay? Trade finance can fund eligible supplier invoices and give Irish importers, retailers and wholesalers up to 180 days to repay.
Read guide →
2 November 2026
Invoice Finance Ireland for Growing SMEs
Release cash tied up in unpaid B2B invoices. Understand factoring, invoice discounting, lender fees and the documents Irish SMEs need.
Read guide →
21 April 2026
Working Capital Finance as Costs Rise for Irish SMEs
How Irish SMEs can manage rising costs and cash-flow gaps: compare working capital finance, understand interest-rate risk and check repayments before borrowing.
Read guide →
16 October 2026
How to Secure Equipment Finance in Ireland: A Guide
Table of Contents How to Secure Equipment Finance in Ireland: Step-by-Step What You'll Need Before You Apply Types of Equipment Finance Available Equipment Finance Application Requirements Documents Lenders Typically Ask
Read guide →
Common questions
Can trade finance help me buy stock for resale?
Yes, a facility may fund eligible supplier invoices for physical goods your business buys and resells. The lender pays the supplier, with repayment terms up to 180 days where agreed. The target profile is at least 12 months trading, around €500,000 annual sales and ideally a profit. Approval depends on the business, supplier and transaction.
Is trade finance the same as credit from my supplier?
No. Supplier trade credit is the payment time your supplier gives you directly. Trade finance is a separate lender facility that can pay an eligible supplier invoice and gives your business an agreed repayment schedule. Check how the facility fits existing supplier terms rather than assuming it extends every bill automatically.
What if builders buy on account and pay later?
Invoice finance may help with qualifying invoices issued to business customers after goods have been supplied. The lender reviews the debtor ledger, customer quality, credit terms and existing finance. A regular ledger facility may suit ongoing trade-account sales. Funding is not a substitute for credit checks, sensible account limits and chasing overdue balances.
Can I fund a single large customer invoice?
One-off or ad hoc invoice finance starts at €100,000. The invoice and customer must meet lender criteria; disputed invoices, credit notes and future orders should not be assumed eligible. A wider ledger facility may suit businesses with several ongoing trade accounts.
Can a term loan cover stock and branch expansion?
A term loan may cover stock and wider business costs for an established merchant. You need at least 12 months trading and one full year's completed accounts, with turnover of €100,000 or more, a net profit and no recent missed payments. The lender also assesses affordability and existing commitments.
Can stock funding and invoice finance work together?
They may address different stages of the cash cycle: paying for stock and collecting cash from eligible customer invoices. Combining facilities requires lender agreement and a review of existing security, assignments and repayment commitments. Do not assume the same transaction can be funded twice.
What should I send to get started?
Send recent business bank statements, latest completed accounts, the amount needed and its purpose. For stock funding, include supplier invoices or pro forma invoices, supplier details and expected stock-sale dates. For invoice finance, include an aged debtor ledger and sample customer invoices and terms. Add equipment quotes if you also need machinery or vehicles.
Do you charge a broker fee?
No. We do not charge clients a fee; lenders pay us a commission when funding completes. Lender interest and charges are separate and should be checked before accepting an offer.
Free to you. Lenders pay us a commission when your loan completes. How we get paid