Menu
Forestry & timber businesses · Ireland
Forestry & timber
business loans.
A replacement forwarder, a sawmill upgrade or a busy contract can tie up cash before customers pay. We help Irish forestry contractors, sawmills, timber merchants and wood-processing businesses compare machinery finance, business loans and eligible invoice funding through specialist and non-bank lenders.
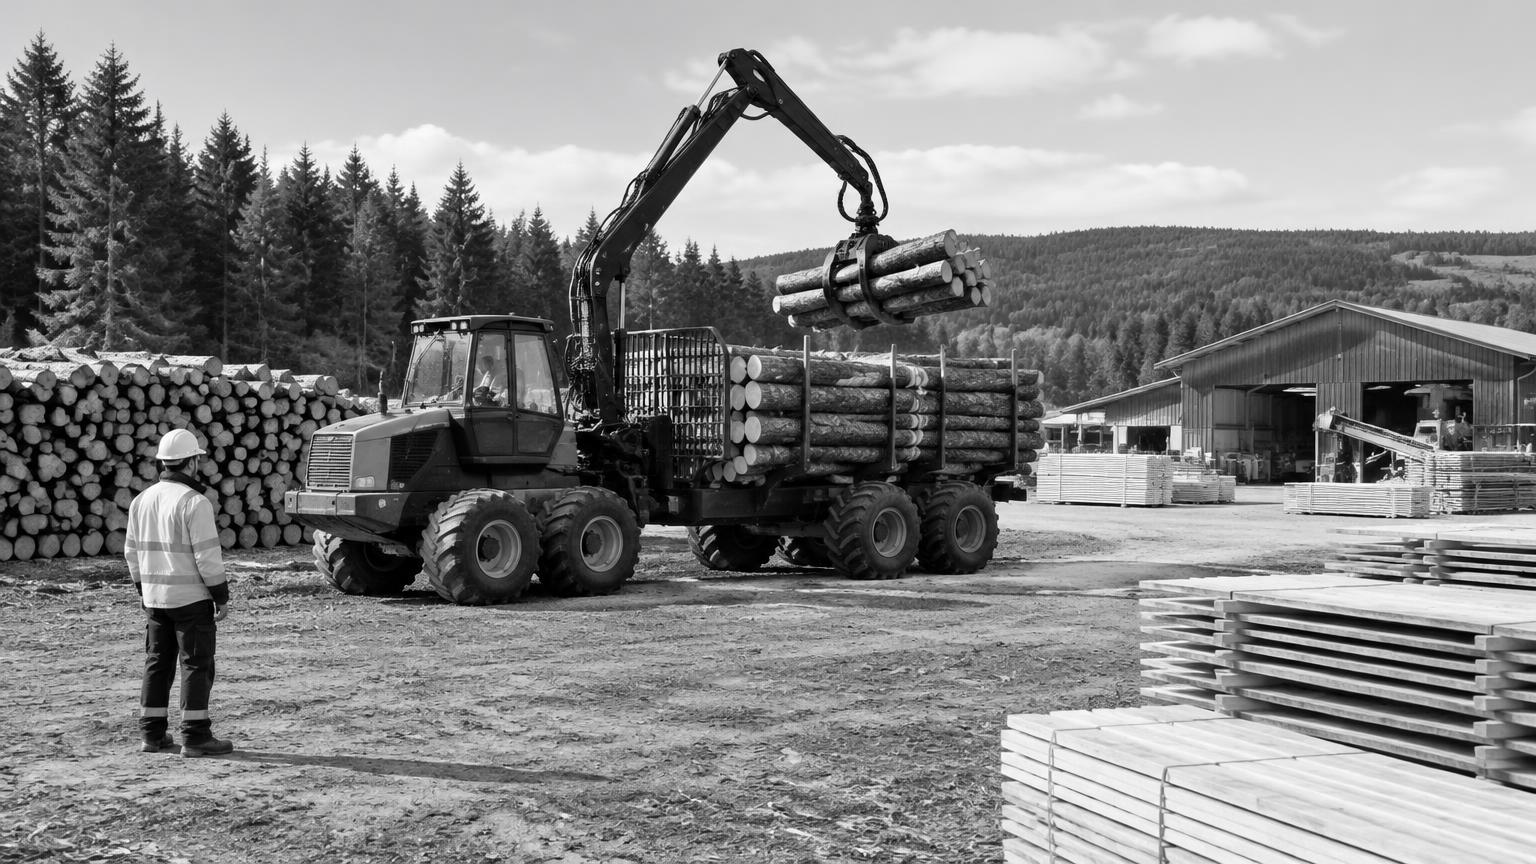
Forestry & sawmill machinery
For suitable equipment used to harvest, handle and process timber.
- Eligible harvesters, forwarders, loaders, chippers and timber-handling equipment
- Suitable sawmill machinery, saws, processing lines and forklifts
- Leasing or hire purchase for suitable new or used machinery
- Equipment-finance deals from €10,000, typically with a 10% dealer deposit
- Specialist machinery, fixed installations and associated works need individual review
- Send a supplier quote with the make, model, age, hours and purchase value
Contracts & working capital
For established businesses paying costs ahead of contract receipts.
- Fuel, wages, repairs, transport, insurance and other business costs
- Contract mobilisation, recruitment and processing-capacity growth
- Term loans require at least 12 months trading and one full year's completed accounts
- Latest accounts showing €100,000 or more turnover and a net profit
- No recent missed payments on business bank statements
- Flexible repayment options may suit businesses from 9 months trading with steady cash flow and around eight or more deposits a month
Commercial invoice finance
For qualifying invoices to sawmills, timber buyers and other business customers.
- Eligible issued invoices for completed forestry services or timber already supplied
- Advances of up to 95% on eligible invoices, subject to assessment
- A wider ledger facility may suit recurring commercial customers
- One-off or ad hoc invoice finance starts at €100,000 per invoice
- Customer quality, concentration, payment terms and contract deductions affect eligibility
- Unbilled work, future harvests and disputed quantities or quality are not automatically eligible
Vehicles & timber stock
For suitable transport assets and eligible goods bought for resale.
- Asset finance for eligible business vans, trucks, trailers and handling equipment
- Include cranes, specialist bodies and conversions in the supplier quote
- Trade finance may fund eligible timber products bought and resold
- Repayment terms up to 180 days, subject to approval and agreed terms
- Trade-finance target profile: at least 12 months trading and around €500,000 annual sales, ideally profitable
- Standing timber, harvesting rights and logs bought for processing need separate review; do not assume eligibility
Business finance only, not personal loans. Unsecured term loans are not registered against property or business assets, but some lenders ask directors for a personal guarantee. All options depend on lender assessment, affordability and asset or invoice suitability. Finance does not replace required felling licences, planning approvals or other permissions.
Match funding to the job and payment cycle
A forwarder used for years is different from this month's fuel bill or a timber-stock purchase. Compare asset finance for suitable machinery and vehicles with term and flexible repayment loans for wider costs. For qualifying commercial invoices, explore invoice finance; eligible resale purchases can be reviewed for trade finance.
If you own suitable machinery, a machinery-secured loan may be another option. Our agri contractor finance, manufacturing finance and builders’ merchant finance pages cover related needs. If you are starting out, see new-business finance.
Guides for your industry
16 October 2026
How to Secure Equipment Finance in Ireland: A Guide
Table of Contents How to Secure Equipment Finance in Ireland: Step-by-Step What You'll Need Before You Apply Types of Equipment Finance Available Equipment Finance Application Requirements Documents Lenders Typically Ask
Read guide →
2 November 2026
Invoice Finance Ireland for Growing SMEs
Release cash tied up in unpaid B2B invoices. Understand factoring, invoice discounting, lender fees and the documents Irish SMEs need.
Read guide →
21 April 2026
Working Capital Finance as Costs Rise for Irish SMEs
How Irish SMEs can manage rising costs and cash-flow gaps: compare working capital finance, understand interest-rate risk and check repayments before borrowing.
Read guide →
20 October 2026
Business Loan With Seasonal Cash Flow: A Practical Guide
How seasonal Irish businesses can borrow well: loan types that suit uneven income, building a cash flow forecast lenders trust, and repayments that match your trading year.
Read guide →
Common questions
Can I finance a harvester, forwarder or sawmill machine?
Suitable new or used forestry and timber-processing machinery may qualify for leasing or hire purchase. Equipment-finance deals start from €10,000, typically with a 10% dealer deposit. The lender reviews the specific machine, age, condition, hours, supplier and your business; not every specialist asset or installation qualifies.
Can a business loan cover fuel, wages and repairs?
A term loan may help an established forestry or timber business cover working capital and contract costs. Lenders need at least 12 months trading and one full year's completed accounts, turnover of €100,000 or more, a net profit and no recent missed payments. Repayments must be affordable alongside existing commitments.
Can invoice finance help while timber buyers take time to pay?
It may suit eligible business-to-business invoices for timber already supplied or forestry services completed, with advances of up to 95% subject to assessment. One-off or ad hoc invoices start at €100,000; a wider ledger facility is another option. Explain measurement adjustments, quality disputes, deductions and customer payment terms. A contract or planned harvest alone is not an issued invoice.
Can trade finance cover timber purchases?
Our trade finance option is aimed at eligible physical goods bought and resold, with repayment terms up to 180 days where agreed. The lender pays the supplier. The target profile is at least one year trading, around €500,000 annual sales and ideally a profit. Timber products bought for resale may be considered; standing timber, harvesting rights or logs transformed through processing should not be assumed eligible.
Can I borrow against machinery I already own?
A machinery-secured loan may be an option, assessed case by case. Lenders generally look for machinery or vehicles under 10 years old with a value of around €15,000 or more per item, owned outright; small outstanding finance can sometimes be settled. Specialist forestry equipment still needs individual review and a satisfactory valuation. This is different from financing a new purchase.
Can you help with timber trucks and trailers?
We can review suitable business vehicles and trailers through specialist asset lenders. Include the vehicle details, age, price, dealer and any crane, body or conversion costs. Eligibility and terms depend on the specific asset and business; ordinary van limits should not be assumed to apply to every timber truck or trailer.
How should I allow for weather and seasonal downtime?
Show when contracts start, when fuel and wages must be paid and when customers settle. Allow for weather interruptions, site access, maintenance, quieter periods and changes in timber prices. Compare repayments with realistic receipts rather than assuming machines work at full capacity all year.
Can a new forestry or timber business apply?
Equipment criteria vary, so a specific supplier quote is a useful starting point. Term loans still require one full year's completed accounts and the turnover and profit criteria. Our new-business finance page explains earlier cash-finance options and support destinations for pre-trading businesses.
What should I send to get started?
Send recent business bank statements, the amount needed and its purpose. Include latest completed accounts for a term loan, machinery or vehicle quotes for asset finance, and an aged debtor ledger with sample invoices for invoice finance. Explain contract schedules, customer payment terms, seasonality and any relevant permissions.
Do you charge a broker fee?
No. We do not charge clients a fee; lenders pay us a commission when funding completes. Lender interest and charges are separate and should be checked before accepting an offer.
Free to you. Lenders pay us a commission when your loan completes. How we get paid