Menu
Cleaning & facilities businesses · Ireland
Cleaning & facilities
business loans.
Staff need paying and sites need servicing before a customer's payment arrives. We help Irish commercial cleaning companies and facilities businesses compare finance for cleaning machines, vans, new contracts and day-to-day cash flow through specialist and non-bank lenders.
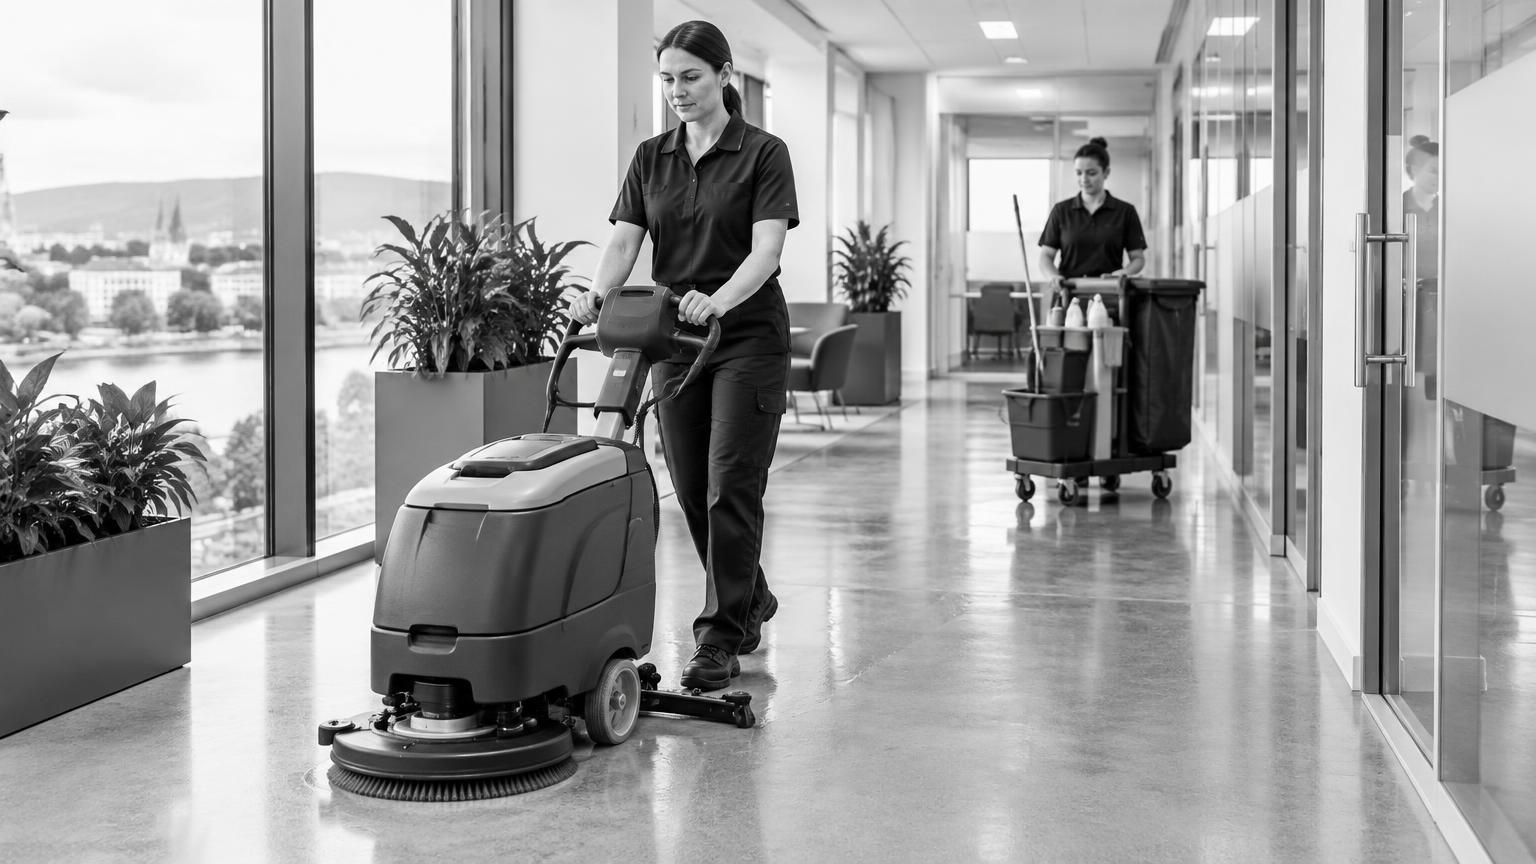
Cleaning equipment & machinery
For suitable equipment your business keeps and uses across contracts.
- Floor scrubbers, sweepers, carpet extractors and suitable commercial cleaning machines
- Leasing or hire purchase for eligible new or used equipment
- A specialist lender can consider no-deposit leasing for suitable smaller cleaning equipment
- Other equipment deals from €10,000, typically with a 10% dealer deposit
- Send a supplier quote showing the machine, age and purchase value
- Cleaning chemicals, disposable supplies and wages are working-capital costs, not equipment assets
Invoice finance for commercial contracts
For eligible invoices already issued to business customers.
- Bridge payroll and supplier costs while commercial customers pay their invoices
- Advances of up to 95% on qualifying invoices, subject to assessment
- A facility may suit a recurring ledger of commercial cleaning or facilities invoices
- One-off or ad hoc invoice finance starts at €100,000 per invoice
- The lender reviews customers, contracts, payment terms and any deductions or disputes
- A signed contract or future work is not the same as an eligible issued invoice
Term loans for new contracts & growth
For established businesses covering upfront costs and wider investment.
- Recruitment, training, uniforms, cleaning supplies and contract mobilisation
- Payroll, marketing, premises and wider business costs
- At least 12 months trading and one full year's completed accounts
- Latest accounts showing €100,000 or more turnover and a net profit
- No recent missed payments on business bank statements
- Flexible repayment options may suit businesses from 9 months trading with steady cash flow and around eight or more deposits a month
Vans & mobile service teams
For moving staff, machines and supplies between customer sites.
- Leasing or hire purchase for eligible new or used business vans
- Single-vehicle purchases and growing fleet requirements can be considered
- Include specialist storage, racking or vehicle-mounted equipment in the quote for review
- Age, value, supplier and affordability determine the available options
- Compare deposits and VAT timing before committing to a vehicle
- An unsecured loan may help with a deposit or private-seller purchase, subject to eligibility
Business finance only. Unsecured term loans are not registered against property or business assets, but some lenders ask directors for a personal guarantee. All funding depends on lender assessment, affordability and the suitability of the equipment or invoices.
Keep contracts moving, not cash tied up
A new site can mean more staff, extra machines and a bigger weekly wage bill before the first customer payment lands. Match the funding to the cost: asset finance for suitable machines, business loans for upfront costs, and invoice finance for eligible issued commercial invoices.
Allow for customer payment runs, holiday cover, supply costs and any contract deductions when judging repayments. Our security company finance and recruitment finance pages cover related payroll-heavy businesses. For an early-stage company, see start-up and new-business finance.
Guides for your industry
2 November 2026
Invoice Finance Ireland for Growing SMEs
Release cash tied up in unpaid B2B invoices. Understand factoring, invoice discounting, lender fees and the documents Irish SMEs need.
Read guide →
16 October 2026
How to Secure Equipment Finance in Ireland: A Guide
Table of Contents How to Secure Equipment Finance in Ireland: Step-by-Step What You'll Need Before You Apply Types of Equipment Finance Available Equipment Finance Application Requirements Documents Lenders Typically Ask
Read guide →
21 April 2026
Working Capital Finance as Costs Rise for Irish SMEs
How Irish SMEs can manage rising costs and cash-flow gaps: compare working capital finance, understand interest-rate risk and check repayments before borrowing.
Read guide →
13 November 2026
Van and Commercial Vehicle Finance: Hire Purchase vs Lease vs Loan
Buying a van for your Irish business? Compare hire purchase, leasing and unsecured loans, including 10% deposits, VAT timing, used vans, Northern Ireland dealers and fleet purchases.
Read guide →
Common questions
Can I finance floor scrubbers and other cleaning machines?
Suitable commercial cleaning equipment may qualify for leasing or hire purchase. A specialist lender can consider no-deposit leasing for some smaller equipment, while other equipment-finance options typically require a deposit. Send a supplier quote so we can check the specific machine and your business circumstances.
Can finance cover wages while commercial customers pay?
Invoice finance may release cash against eligible issued business-to-business invoices, with advances of up to 95% subject to lender assessment. A wider ledger facility may suit ongoing contracts. One-off or ad hoc invoice finance starts at €100,000 per invoice. Household customer invoices and disputed bills should not be assumed to qualify.
Can I fund the upfront cost of a new cleaning contract?
A term loan may help an established business cover recruitment, training, uniforms, supplies and wages before billing starts. The lender checks affordability and your existing commitments. Invoice finance may become relevant once eligible work has been completed and invoiced; a contract alone does not automatically qualify.
What are the term-loan requirements?
At least 12 months trading and one full year's completed accounts, with turnover of €100,000 or more, a net profit and no recent missed payments on recent business bank statements. The lender also assesses affordability and existing borrowing.
Do you help facilities maintenance businesses as well as cleaners?
Yes. We can review suitable business equipment, vans, working capital and qualifying commercial invoices for facilities service businesses. Tell us which services you provide and what the funding will pay for, rather than assuming every item or contract is eligible.
Can a newer cleaning company apply?
Equipment and vehicle criteria vary by lender. Some flexible repayment options start from 9 months trading with steady cash flow; higher-risk, more expensive revenue-based cash finance may be considered from 90 days. Term loans still need a full year's completed accounts and the turnover and profit criteria. Pre-trading businesses should explore banks, Microfinance Ireland and National Enterprise Hub supports.
What should I send to get started?
Send recent business bank statements, the amount needed and its purpose. Include supplier or vehicle quotes for equipment finance, and your latest completed accounts for a term loan. For invoice finance, include an aged debtors list, sample invoices and customer contract terms. Explain payroll dates, customer payment terms and the start date of any new contracts.
Do you charge a broker fee?
No. We do not charge clients a fee; lenders pay us a commission when funding completes. Lender interest and charges are separate and should be checked before accepting an offer.
Free to you. Lenders pay us a commission when your loan completes. How we get paid