Menu
Garden centres & nurseries · Ireland
Garden centre & nursery
business loans.
Garden centres and nurseries live by the seasons: stock is bought and grown months before the spring rush, the tills quieten over winter, and most sales come through the card machine. We help Irish garden centres and nurseries compare working capital, merchant cash advances and asset finance through specialist lenders.
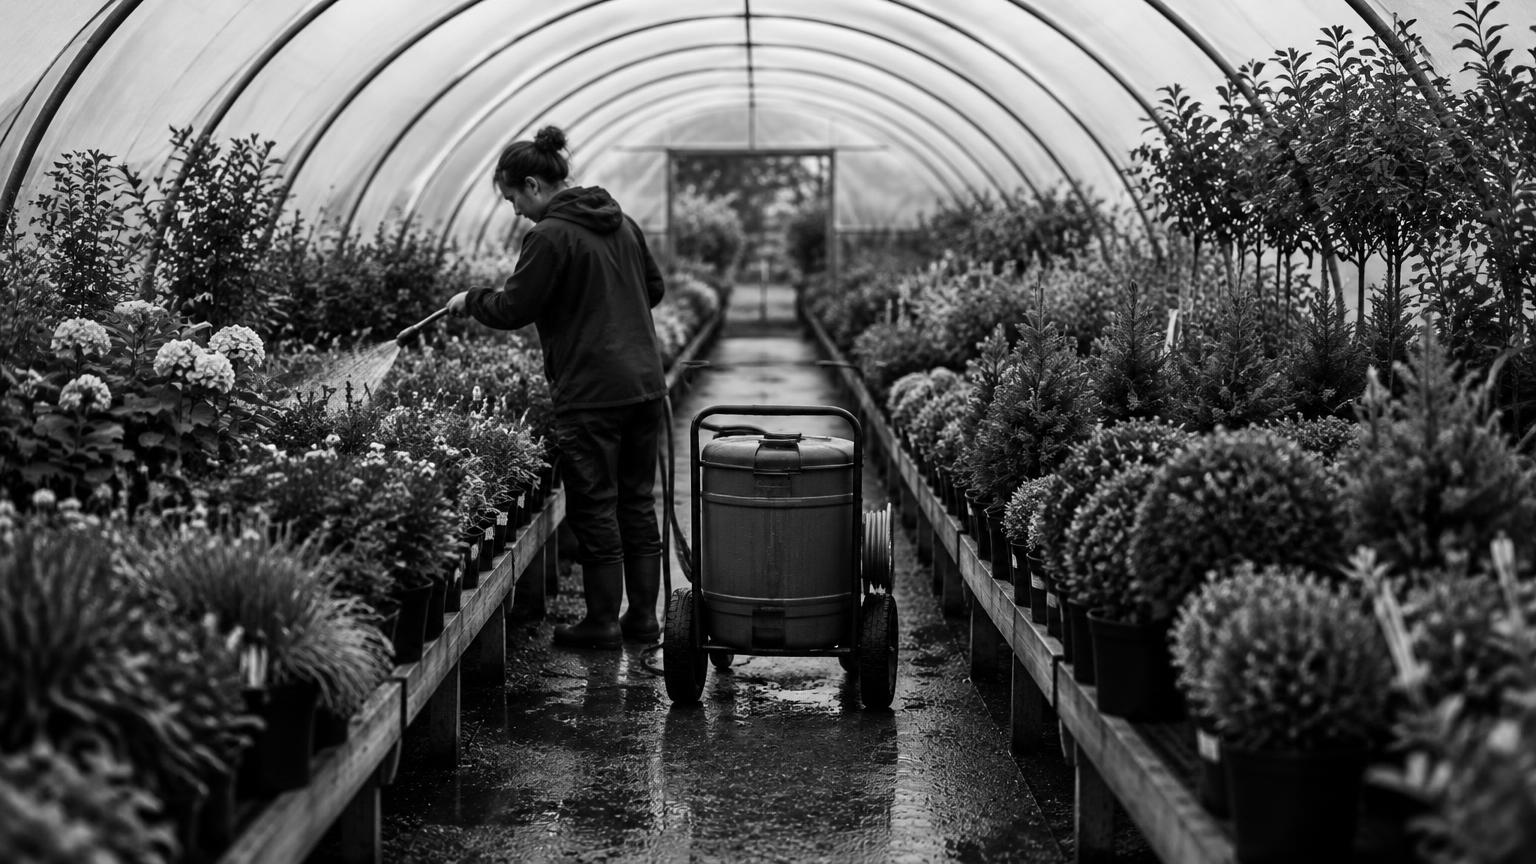
Working capital for seasonal stock
Buy plants, trees, compost and garden products ahead of the spring and summer rush, when the money goes out months before the till fills up.
- Unsecured term loans from €5,000 to €500,000 for established businesses
- Fund a bulk buy of stock ahead of the planting season
- Cover wages and suppliers through the quiet winter months
- From 12 months trading with one year’s accounts for term loans
- Repayments matched to how the season comes in
Merchant cash advance from 90 days trading
If most of your sales come through the card machine, an advance against future card takings can work from much earlier in the business's life.
- From around 90 days trading
- Card takings of about €5,000 a month or more
- Repayments flex with your card sales — quieter months cost less
- Suits seasonal businesses where spring and summer carry the year
- A faster option when a traditional loan isn't available yet
Asset finance for equipment and vehicles
Spread the cost of the kit the business runs on instead of paying for it in one go.
- Hire purchase or leasing for suitable new or used assets
- Delivery vans and trucks, forklifts, tractors, polytunnels, irrigation and tills
- Leasing with no deposit on smaller items, and finance on suitable vehicles from €10,000
- A supplier quote helps us compare the options
- In some cases, loans secured on equipment you already own can work — assessed case by case
Finance is subject to lender assessment. Unsecured term loans are not registered against property or business assets, but some lenders ask directors for a personal guarantee. Equipment-secured loans are assessed case by case.
Why garden centres come to us
The money goes out months before it comes in
A garden centre's year is decided in spring, but paid for in winter. Plants and trees are ordered and potted months ahead, polytunnels and benches need to be ready, and staff are taken on before the first busy weekend. Then the year turns again: Christmas trees and winter stock help, but the quiet months still have to be funded. Nurseries growing their own stock carry the gap even longer.
Working capital covers seasonal stock and wages, a merchant cash advance repays as a share of card sales so quiet months cost less, and asset finance spreads the cost of delivery vehicles, forklifts, polytunnels and tills over their working life.
Coming from a different angle? Our merchant cash advance page explains how card-based advances work, the retail page looks at funding across shops more broadly, and the unsecured business loans page covers term-loan criteria in detail.
Guides for your industry
20 October 2026
Business Loan With Seasonal Cash Flow: A Practical Guide
How seasonal Irish businesses can borrow well: loan types that suit uneven income, building a cash flow forecast lenders trust, and repayments that match your trading year.
Read guide →
3 November 2026
Is a Merchant Cash Advance Right for Your Irish Business?
How merchant cash advances work in Ireland: card-sales repayments, costs, eligibility from 90 days trading and the alternatives to compare before applying.
Read guide →
16 October 2026
How to Secure Equipment Finance in Ireland: A Guide
Table of Contents How to Secure Equipment Finance in Ireland: Step-by-Step What You'll Need Before You Apply Types of Equipment Finance Available Equipment Finance Application Requirements Documents Lenders Typically Ask
Read guide →
8 November 2026
How Quickly Can SMEs Borrow Money in Ireland?
A supplier deadline, a replacement vehicle or cash tied up in invoices: find out what speeds up Irish SME finance, what to prepare and how to choose funding that fits.
Read guide →
Common questions
Can I borrow to buy stock ahead of the spring season?
Yes. Working capital finance can cover plants, trees, compost and garden products bought months before the busy season, so a full yard in March doesn't mean an empty bank account in February.
My business is seasonal — does that count against me?
Not necessarily. Lenders who understand retail look at the full year's trading, and a merchant cash advance repays as a share of card sales, so quieter winter months cost less. Seasonality is normal for the sector — the key is showing the pattern clearly.
How soon can a newer garden centre or nursery get finance?
A merchant cash advance can work from around 90 days trading with card takings of about €5,000 a month or more. Flexible repayment loans can work from around 9 months with steady deposits, and unsecured term loans typically need 12 months trading with one year's accounts.
What do lenders look for?
For unsecured term loans, lenders typically want at least 12 months trading with one year's accounts, turnover of €100,000 or more, a net profit and clean recent bank statements. Limited company, Sole trader, Partnership accounts can all work.
Free to you. Lenders pay us a commission when your loan completes. How we get paid